What the City of Barrie lets you add to your lot
Barrie allows up to four homes on one residential lot. For most owners, that means room for as many as three extra units beside the house you live in now, if your lot meets the zoning rules. The City calls each one an additional residential unit, or ARU.
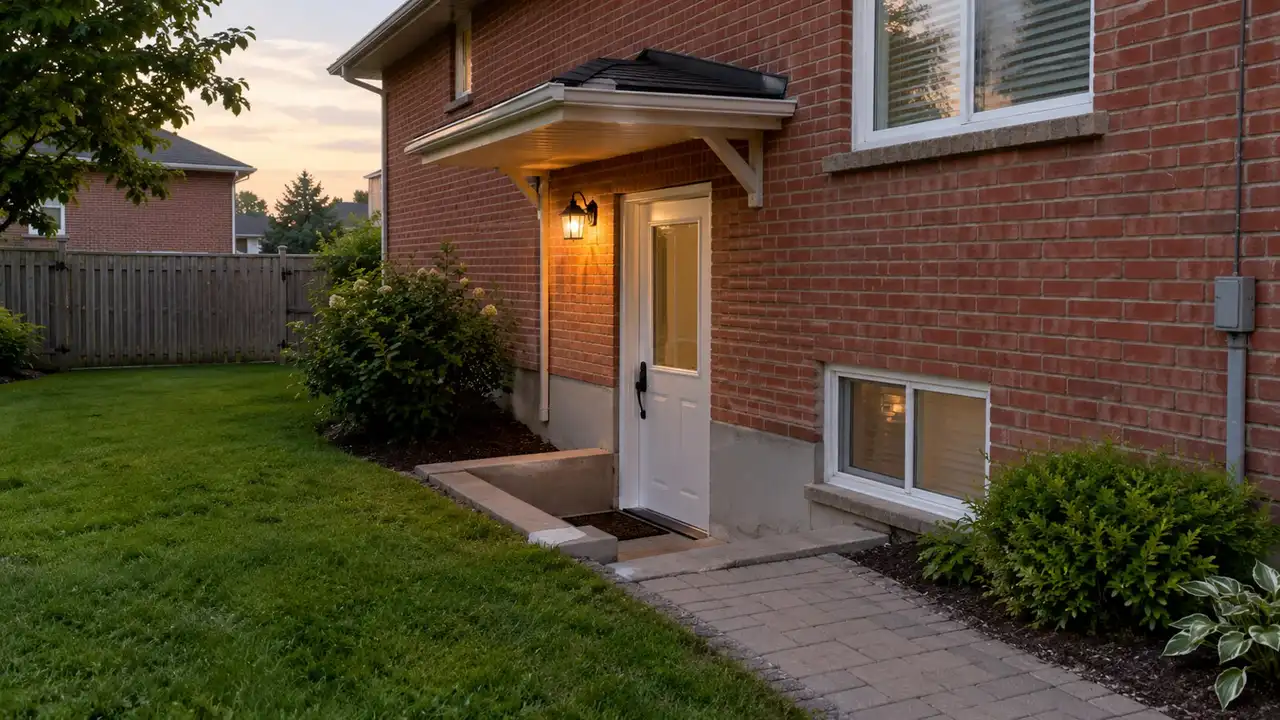
A suite can sit inside your house, be attached to it, or stand on its own in the yard. In Barrie, the usual versions are a basement apartment, an in-law suite, a coach house over a garage, or a new addition. Detached houses, semi-detached houses and townhouses all qualify.
The zoning checklist is short but firm:
- Parking: one space per unit, at least 5.5 m long and 2.7 m wide. Cars may park one behind the other.
- A walkway: a clear path at least 1.2 m wide from the street or driveway to the suite’s door.
- Setbacks and size: set distances from your lot lines, plus height, size and planting-buffer limits for a detached unit.
- A survey: the City says you’ll need one from an Ontario Land Surveyor.
Some lots near a creek, wetland or the Kempenfelt Bay shoreline are regulated by the Lake Simcoe Region Conservation Authority or the Nottawasaga Valley Conservation Authority. If yours is, you need their permit before you apply for a City building permit. A designated heritage home may need its own approval too.
What Barrie’s 2026 fee break covers, and what it leaves out
For applications made in 2026, the City has cut building permit application fees for new suites by 50%, including the zoning and water fees on that permit. You can get the other half back as well. To qualify, the suite must pass its final interior inspection, or a new detached unit must reach occupancy, within 12 months of the permit being issued.
| Date | What has to happen |
|---|---|
| December 31, 2026 | Your permit application and incentive form are in, and the permit is issued |
| 12 months after the permit | Final inspection or occupancy, for the full rebate |
| December 31, 2027 | The project is finished, at the latest |
The break does not apply to the pre-screening fee, permits for the main house, demolition, site servicing, revisions or re-inspections. Development charges are excluded too. Barrie’s suite page says up to two added units per property may be exempt from development charges, and a third would pay them. The City works out the permit fee from the size of the unit, so ask for a figure on your own plans.
For a detached unit, the City also offers a catalogue of ready-made designs. Using one can save design fees and time. You still need a permit, a site and grading plan, a licensed builder and every inspection.
Paying for the build with a reverse mortgage
A reverse mortgage pays your builder from your home’s value instead of your savings, and there are no monthly mortgage payments. You keep ownership. Property tax, home insurance and upkeep stay yours, and keeping them current is a condition of the loan.
How much is available depends on the youngest owner’s age and the appraised value, which is the price a licensed appraiser sets after visiting. On Barrie’s September 2026 benchmark home of $617,100, the limits work out like this:
| Youngest owner | Up to about | On a $617,100 Barrie home |
|---|---|---|
| 65 | 50.55% | about $312,000 |
| 70 | 52.85% | about $326,000 |
| 75 | 57.75% | about $356,000 |
| 78 and older | 60% | about $370,000 |
Each figure is a ceiling, not an offer, and any mortgage you still carry is paid off from it first. The Barrie reverse mortgage calculator shows your own figure and a 15-year chart of home value, loan and equity.
You owe no tax on the money because it’s borrowed, and your Old Age Security and Guaranteed Income Supplement (GIS) don’t change. Interest is added to the balance and compounds twice a year, the way it does on any Canadian mortgage. Advertised five-year fixed rates ran from 6.23% to 6.94% when checked on October 2, 2026. One-time costs, from the appraisal to your own lawyer, come to about $2,000 to $3,500 all in.
An example, not a quote: you take $100,000 to finish a basement suite, at an example rate of 6.44%. With no payments made, the balance would be about $137,300 after 5 years and about $188,500 after 10. When the loan comes due, the amount owed can never be more than your home’s fair market value, provided taxes, insurance and upkeep were kept up. It’s typically called the no negative equity guarantee. The Barrie cost guide breaks down every fee and penalty.
The principal residence rule, and renting the suite out
Every reverse mortgage lender requires the home to be your principal residence. You can live in the main house and rent out the suite. You could also move into the suite yourself and let family take the main floor, as long as the property is still your home.
Lenders differ on homes with more than one unit, and some are more at ease with a finished, registered suite than others. So tell Richard about the suite when you apply, whether it’s built, under way or only an idea. Your application then goes only to the lender you choose from those that accept it.
Two cautions before you count on rent:
- Rent is taxable income. Reverse mortgage money is not, but the rent you collect goes on your tax return. GIS is paid only below set income limits, so rent can shrink it. Ask your accountant first.
- Fire safety rules changed this year. Ontario Fire Code updates in force since January 1, 2026 require carbon monoxide alarms in more kinds of units. Barrie registers your suite on its own once the final inspections pass.
Tell your home insurer about the suite and any tenant as well, since full coverage is a condition of the loan.
County and federal money, and how it fits with a reverse mortgage
The County of Simcoe runs a Secondary Suites Program, and the City points Barrie owners to it. It offers up to $50,000 per property to create a suite or garden suite, as a 15-year forgivable loan. A forgivable loan shrinks a little each year you follow its rules, until nothing is owed. Barrie owners approved for it could also qualify for a $15,000 Barrie Bonus through the City’s Housing Community Improvement Plan.
The conditions are strict:
- Rent must stay at or below Canada Mortgage and Housing Corporation’s average market rent for 15 years.
- Your tenant’s household income must be under a provincial limit, and you report rents every year.
- Construction must start within 90 days of approval.
- The loan is registered on your title as a mortgage.
That last point matters for a reverse mortgage. The County’s fact sheet says it will postpone its security in favour of a new first mortgage, and it doesn’t say whether a reverse mortgage counts as one. Ask the County and Richard before applying to both, so one doesn’t block the other.
The City also mentions the federal Multigenerational Home Renovation Tax Credit. It helps pay for a unit where a senior or an adult with a disability lives with family. If the suite is for you, see making your Barrie home accessible for ramps, grab bars and a level entrance.
A suite for family instead of a tenant
The City lists housing family members as one of the main reasons to build a suite. A grandchild saving for a first home, or a daughter who helps with your care, could live steps away with her own kitchen and door. If helping family buy a place of their own is the goal, read about giving a living inheritance in Barrie.
A new unit can change your property’s assessed value, which MPAC sets, not the City. Before you budget, see how property tax works for Barrie seniors.
If Barrie annexed your property in 2026
Land that joined Barrie from Oro-Medonte and Springwater on January 1, 2026 follows different rules for now. An Interim Control By-law lets those properties be used only as they were on that date, until it’s lifted or expires on December 23, 2026. The former township zoning by-laws still apply until Barrie passes new ones. Check with the City before you plan a suite there, and read more on the rural homes around Barrie page.
How Richard helps you with this
- Checks which lenders accept a home with a suite, built or planned
- Works out how much you could get at your age before you hire a builder
- Talks through timing: money before construction, or after the suite is done
- Spots a County suites loan or other charge on your title early
- Compares every reverse mortgage lender in Canada on rate, fees and penalty
- Explains how the appraiser values your home with or without the suite
- Helps you find your own lawyer for independent legal advice
- Answers your family's questions by email, with them copied if you like
Barrie guides that go deeper
- How much does a reverse mortgage cost in Barrie?
- What property tax help can seniors get in Barrie?
- What are home prices in Barrie right now?
Sources
Figures checked October 16, 2026.
- City of Barrie, Additional Residential Units (checked October 16, 2026)
- City of Barrie, 2026 Additional Residential Unit Incentives Program (checked October 16, 2026)
- County of Simcoe, Affordable Housing Programs (checked October 16, 2026)
- County of Simcoe, Secondary Suites Program Fact Sheet 2025 to 2026
- City of Barrie, Boundary Expansion (checked October 16, 2026)
- TRREB, Simcoe County Market Watch, September 2026 (released October 6, 2026)
- Government of Canada, Guaranteed Income Supplement eligibility (October 2026)
- reversemortgagebroker.ca, Best reverse mortgage companies in Canada (rates checked October 2, 2026)