For Barrie homeowners 55 and older
Barrie Reverse Mortgages: Turn Your Home's Value Into Tax-Free Cash While You Keep Living There
A licensed, independent Ontario broker checks CHIP, Equitable Bank, Home Trust and Bloom against your Barrie home and your plans. You see how much you could get, the rates and every cost, hidden fees included, before you decide a thing. No monthly mortgage payments are required. It's free, with no sales pressure.
No cost · No credit check · No sales pressure
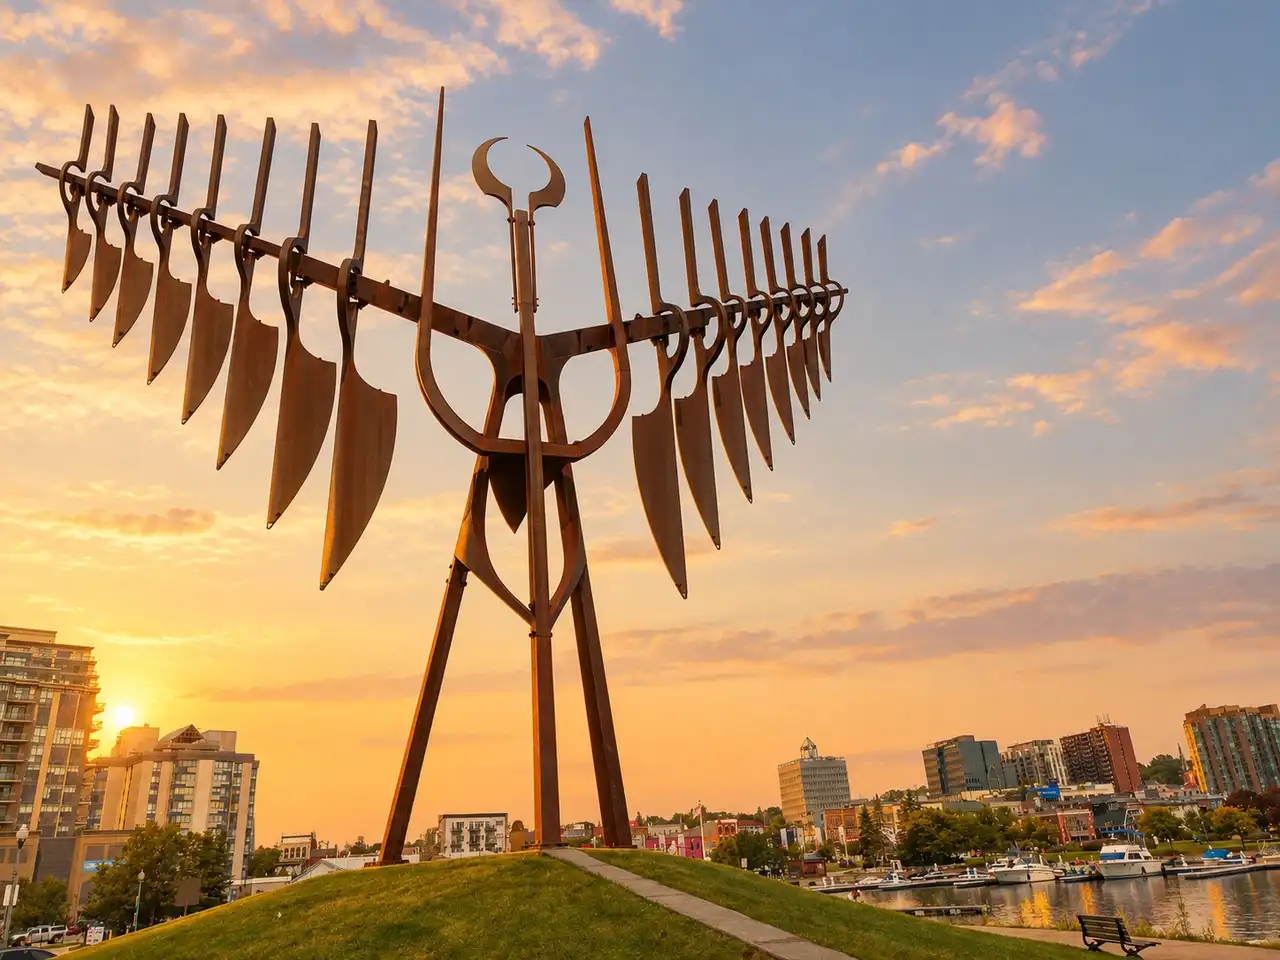
Photo: Raysonho @ Open Grid Scheduler / Scalable Grid Engine, CC0 (public domain), via Wikimedia Commons. Lighting edited.
What a typical Barrie home could give you
On the September 2026 Barrie benchmark price of $617,100. TRREB, September 2026
- Youngest owner 65
- $312,000
- up to 50.55% of the value
- Youngest owner 70
- $326,000
- up to 52.85% of the value
- Youngest owner 75
- $356,000
- up to 57.75% of the value
- Youngest owner 78+
- $370,000
- up to 60% of the value
These are ceilings, not offers. The appraisal of your own home and the lender you choose set your real figure.
- For Barrie homeowners 55 and older
- No monthly mortgage payments required
- You stay the owner
- The money is tax-free
- Your own lawyer explains it before you sign
- Never owe more than the home is worth when it comes due (taxes, insurance and upkeep kept up)
Start Here: What Barrie Homeowners Ask First
Why Barrie Homeowners Look Into a Reverse Mortgage
23,515 Barrie residents are 65 or older, and 30.6% of Barrie homeowners have no mortgage at all (Statistics Canada, 2021 Census Profile, City of Barrie). For many of them, the house is where most of their money sits. These are the four reasons that come up most.
Barrie winters are hard on an older house, and on you
Stairs to the only bathroom, a tub you climb into, a long driveway to clear. Changing the house to fit you takes money a pension wasn't planned for.
Paying for changes to your home
The care you need goes past the hours you're given
Publicly funded home care covers some visits. Extra hours from a personal support worker are paid privately, week after week.
Paying for help at home
Your children want to buy a home of their own
You can help now, while you get to see it, instead of leaving it all in the will.
Helping a child buy a home
Condo fees and living costs keep climbing
Condo owners qualify too. Each lender also looks at your building, so which lender you choose matters more.
Reverse mortgages on Barrie condos
Five Ways Barrie Homeowners Use a Reverse Mortgage
The money is yours to use as you see fit. Each page below covers one use, with the Barrie costs, programs and rules that go with it.


Free Help From a Broker Who Checks All Four Lenders for You
Canada has just four reverse mortgage lenders, and no two set the same limits, rates or fees, so a single Barrie house can draw four very different offers. That's why Richard Hopkins, Mortgage Broker, looks at all of them for you: he compares every reverse mortgage lender in Canada, and his brokerage is paid by your chosen lender once the mortgage funds.
-
Every lender compared in one place
A lender can only offer its own mortgage. Here, every lender is compared for your Barrie home, and the best deal for your goals comes to your inbox.
-
A recommendation based on your situation
Richard also arranges home equity lines of credit and refinances, so he can point you to the option with the best overall value, whatever it is.
-
Sometimes a Lower Rate or Set-Up Fee
A broker can sometimes get a rate below the posted one, or a smaller set-up fee. It costs you nothing extra.
-
Your family can follow along
Everything comes by email, so you can reread it at your own pace. A son or daughter can be copied on every message, if you like.
From First Question to Money in Your Bank Account: The Seven Steps
Email and phone cover nearly everything. The exceptions are one appraiser's visit to your home and one meeting with your own lawyer. You're free to stop at any point, and no part of it is final until that lawyer has walked you through the mortgage.
-
Free estimate
Start with the free estimate form: a handful of questions, about 90 seconds of your time. Nobody looks at your credit at this stage.
-
Your options by email
Working for you, Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada. You get an email with the amount your home could give you and the lenders that suit it, and he asks what amount you have in mind. You never have to take the most.
-
Quick application
Once you've chosen an option, fill out a quick form and send a few documents. Your credit is checked once, and your application goes only to the lender you choose.
-
Approval
The lender usually sends its mortgage commitment letter within a day or two.
-
Appraisal
Richard arranges the appraisal. An appraiser visits your home once to confirm what it's worth.
-
Independent legal advice
You sit down with a lawyer you pick, who works for you alone and takes you through the mortgage line by line.
-
Closing
The lender sends the money to the lawyer or title company doing the closing. They pay off your current mortgage, any other debts on the home and the costs, then deposit the remaining money into your bank account.
What a Reverse Mortgage Costs
Owning in Barrie doesn't change the price. Here is what every Ontario borrower pays, and when each figure was last confirmed.
Advertised 5-year fixed rates
6.23% to 6.94%
Lowest to highest of the four lenders' posted rates on October 2, 2026. The interest is added to what you owe, with no monthly mortgage payment required.
One-time costs, all in
$2,000 to $3,500
Covers the appraisal, the lender's set-up fee, the legal work to close and your own lawyer. Most of this comes out of the mortgage money on closing day.
Your own lawyer (independent legal advice)
$800 to $1,200
Required on every reverse mortgage: a Barrie lawyer acting for you alone. That is the typical Ontario fee, already counted in the total beside it.
Richard's help costs you nothing: the lender pays the brokerage. For the full picture, including how the loan grows over 5 and 10 years, read what a reverse mortgage costs in Barrie.
Three Ways to Get Money From Your Barrie Home
When a Barrie homeowner needs money from the house, it usually comes down to these three. The right one is the one with the best overall value for your plans.
| Question | Reverse mortgage | Home equity line of credit (HELOC) | Sell and move |
|---|---|---|---|
| Do you keep your home? | Yes | Yes | No |
| Monthly payments | None required. You keep paying taxes, insurance and upkeep. | Yes, at least the interest each month | Rent or condo fees at your next home |
| How you qualify | Mostly your age and your home. Credit is reviewed, but there's no bank-style income test. | Income and credit, the same test as a regular mortgage | No test |
| Can the lender cut it back or freeze it? | No | Yes | Does not apply |
| One-time costs | About $2,000 to $3,500 | Legal and appraisal fees, which some banks pay | Real estate commission and HST, Ontario land transfer tax on your next home, lawyers, movers |
Barrie has no city land transfer tax; only Ontario's applies. The full cost of moving is worked out in what downsizing in Barrie costs.
Barrie Lets Owners 65 and Older Freeze Their Property Tax
The City of Barrie's Property Tax Deferral Program lets owners 65 or older, or anyone receiving Ontario Disability Support Program benefits, keep paying the tax amount from the year before they first apply. The increase is deferred with no interest, and the total is repaid when the home is sold. You apply again by August 31 every year (City of Barrie).
A reverse mortgage works differently: your property taxes must stay paid, and any deferred or unpaid tax is usually paid off when the reverse mortgage closes. For some owners, the deferral is all they need. For others, taxes are only one of several bills.
Help in Every Barrie Neighbourhood
Allandale, Painswick, Holly, the north end or the waterfront: one set of rules covers them all. The house is what differs, from its age and type to what it would sell for.


Barrie reverse mortgage questions
How much can I get with a reverse mortgage on my Barrie home?
It mostly depends on the youngest owner's age and the appraised value of your home. On Barrie's September 2026 benchmark price of $617,100 (TRREB, September 2026), the most is about $312,000 at 65 and about $356,000 at 75. You don't have to take it all, and interest only runs on what you take. The Barrie calculator starts from your type of home.
Are reverse mortgage rates different in Barrie?
No. Lenders don't set rates by city, so a Barrie home gets the same advertised rates as any Ontario home. The four lenders advertised 6.23% to 6.94% for a 5-year fixed term when checked on October 2, 2026. Through a broker, the rate can sometimes come in under the posted one.
Do I still own my home?
Yes. The title stays in your name, and the house stays yours. A reverse mortgage is registered on it the same way any bank mortgage is. Your jobs stay the same as now: property tax, home insurance and looking after the place.
Can the debt ever end up bigger than my house?
No. You can never owe more than your home is worth when the mortgage comes due. That holds while you keep the house taxed, insured and looked after. It's typically called the no negative equity guarantee, and every reverse mortgage lender in Canada builds this protection in.
Can I use Barrie's property tax deferral and a reverse mortgage together?
Usually not. A reverse mortgage requires your property taxes to be paid, and any amount deferred with the City is usually paid off from the reverse mortgage at closing. For some owners the City's deferral alone is enough. Barrie property tax help for seniors explains both.
Will I have to go anywhere in person?
Just once, to see your own lawyer. Everything with Richard runs by email, phone or video, and family can be copied. Before signing, you meet a lawyer who represents only you, normally at their Barrie office, for a fee of roughly $800 to $1,200.
More answers are in the Barrie reverse mortgage guides. To test your own situation, take the 10-question assessment.